Against the Earnings Bet: Why Probability Theory Favors Structure Over Direction
Photo: U.S. Navy photo by Petty Officer 2nd Class Delaney Jensen, Public domain, via Wikimedia Commons
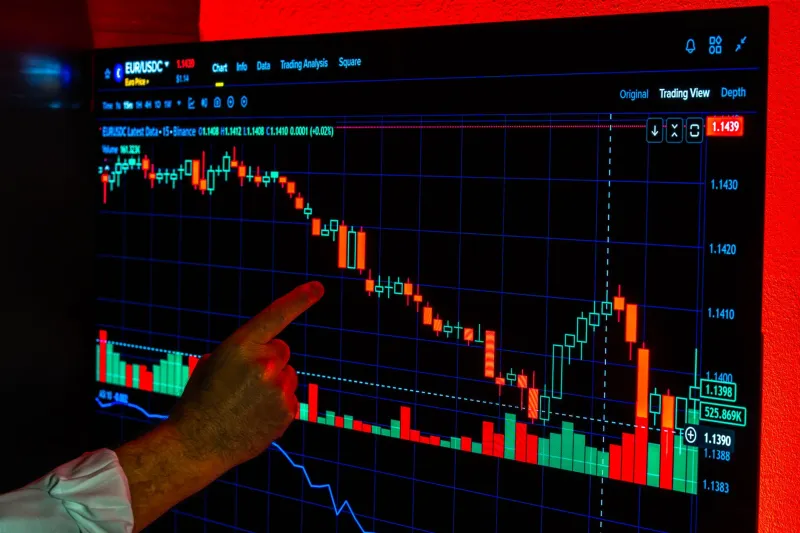
Every quarter, the earnings calendar arrives like a recurring temptation. A company is reporting after the bell. The setup looks clean — strong momentum into the print, whisper numbers trending above consensus, a sector tailwind. The trader sizes up, takes a position, and waits. By the following morning, the stock has gapped down 11% on guidance that missed by a fraction. The position is underwater before the opening bell rings.
This scenario is not the result of poor research or bad luck in isolation. It is the predictable consequence of engaging in a game where the structural odds are systematically misaligned with the directional trader's expectations. The mathematics of earnings-period trading deserve a more rigorous examination than most retail participants ever conduct.
The Implied Volatility Crush Problem
Options markets price uncertainty. In the days and weeks preceding a scheduled earnings announcement, implied volatility — the market's forward-looking estimate of price movement embedded in option premiums — rises steadily as participants hedge exposure and speculative interest builds. By the session immediately before the announcement, implied volatility in near-term options frequently reaches levels that are historically elevated relative to that security's realized volatility.
The moment the announcement is made, uncertainty resolves. Whether the news is good, bad, or ambiguous, the unknown has become known, and implied volatility collapses rapidly — a phenomenon traders refer to as the volatility crush. For a trader who purchased a call option in anticipation of a positive earnings beat, this creates a paradoxical outcome: the stock may move in the anticipated direction, yet the option loses value because the premium paid for uncertainty has been permanently destroyed.
Research examining S&P 500 component earnings across multiple cycles consistently demonstrates that implied moves — the magnitude of price change that option pricing implies will occur — overestimate actual realized moves more often than not. A study of large-cap earnings announcements between 2015 and 2023 found that realized moves fell short of implied moves in approximately 68% of cases. The options market, aggregating the bets of all participants, systematically overprices earnings uncertainty. This is not an accident; it reflects the consistent demand for earnings-period hedges, which inflates premiums beyond what subsequent price action justifies.
For the trader purchasing options directionally into earnings, this structural overpricing functions as a tax on every position, assessed regardless of whether the directional call proves correct.
Gap Risk and the Limits of Stop-Loss Discipline
Traders who prefer equity positions over options often cite their ability to manage risk through disciplined stop-loss execution. This reasoning, sound in most contexts, breaks down completely in the earnings environment. The mechanism is gap risk — the possibility that a security opens at a price dramatically different from its previous close, bypassing any stop order placed at an intermediate level.
Gap risk is not a tail risk in earnings-period trading. It is a central feature of the experience. For US-listed equities reporting after the close or before the open, the entire price adjustment process occurs in after-hours or pre-market sessions where liquidity is thin and price discovery is incomplete. By the time the regular session opens, the gap has already materialized. A stop order placed at a 5% loss threshold provides no protection against a 14% overnight gap.
The psychological dimension of this reality is worth examining directly. Many traders understand gap risk abstractly but discount it emotionally because they are anchored to their entry price and the analysis that supported it. The cognitive dissonance between "my analysis is correct" and "I could lose 15% overnight with no ability to manage it" is uncomfortable, and traders frequently resolve that dissonance by underweighting the risk rather than by reconsidering the position. This is a textbook example of the confirmation bias that erodes long-term performance.
What the Historical Distribution of Earnings Outcomes Actually Shows
A useful exercise is to examine the full distribution of earnings outcomes rather than focusing on memorable individual cases. When researchers analyze the post-announcement one-day returns of Russell 2000 components — a universe particularly relevant to active US equity traders given its breadth and volatility — the distribution is strikingly wide and fat-tailed in both directions.
More importantly, the distribution does not cluster predictably around consensus estimate outcomes. Companies that beat earnings-per-share estimates by meaningful margins frequently decline; companies that miss estimates occasionally rally on forward guidance. The relationship between the fundamental event and the subsequent price action is mediated by positioning, by the quality of prior expectations already embedded in the stock price, and by macro conditions that may have shifted since analysts last updated their models. A directional bet on earnings is not simply a bet on whether the company will perform well — it is a bet on a multi-variable outcome that includes all of these factors simultaneously.
Backtesting systematic directional earnings strategies across large samples of US equities produces consistently sobering results. Long strategies that buy stocks entering earnings with strong momentum and sell immediately after the announcement show Sharpe ratios well below 0.5 in most configurations, with drawdown profiles that are difficult to sustain psychologically even when the long-run expectancy is marginally positive.
Structurally Superior Alternatives for the Active Trader
Acknowledging that directional earnings bets are mathematically disadvantageous does not require abandoning the earnings calendar as a source of opportunity. It requires reorienting toward structures that are aligned with — rather than opposed to — the statistical properties of the earnings environment.
Volatility Arbitrage via Short Premium Strategies. Given the consistent tendency for implied volatility to overestimate realized moves, selling options premium into earnings — through defined-risk structures such as iron condors or short strangles with purchased wings — places the trader on the statistically favorable side of the implied-versus-realized volatility relationship. The risk is a gap move that exceeds the structure's defined boundaries; position sizing must reflect this possibility.
Pre-Announcement Accumulation Patterns. Institutional positioning ahead of earnings sometimes leaves detectable footprints in options flow, dark pool activity, and unusual volume in specific strike clusters. Traders who identify these patterns and build positions before the implied volatility expansion — rather than into it — capture the premium inflation as a tailwind rather than paying it as a cost.
Earnings-Adjacent Spread Trades. Rather than betting on the announcing company, some of the most consistent earnings-related opportunities involve trading the spread between the reporting company and a closely correlated peer that has not yet announced. If a major semiconductor manufacturer reports results that reveal sector-wide demand trends, the information content of that announcement is relevant to competitors whose valuations have not yet adjusted.
Reframing the Quarterly Ritual
The earnings calendar is one of the most psychologically compelling features of US equity markets. It creates urgency, narrative, and the appearance of actionable information arriving at a predictable schedule. These qualities make it appealing to active traders conditioned to seek catalysts.
The more productive reframing is to treat the earnings calendar not as a trigger for directional bets but as a source of volatility intelligence and relative-value signals. The trader who approaches each quarterly cycle asking "what does this announcement tell me about relationships and mispricings across the market?" is operating at a fundamentally different — and more durable — level than the trader asking "will this stock go up or down tonight?"
Precision in trading means understanding not only where the opportunities lie, but where the structural disadvantages are concentrated. Earnings-period directional bets, for most active traders, belong firmly in the second category.